Stacking Layers Creates Blind Spots
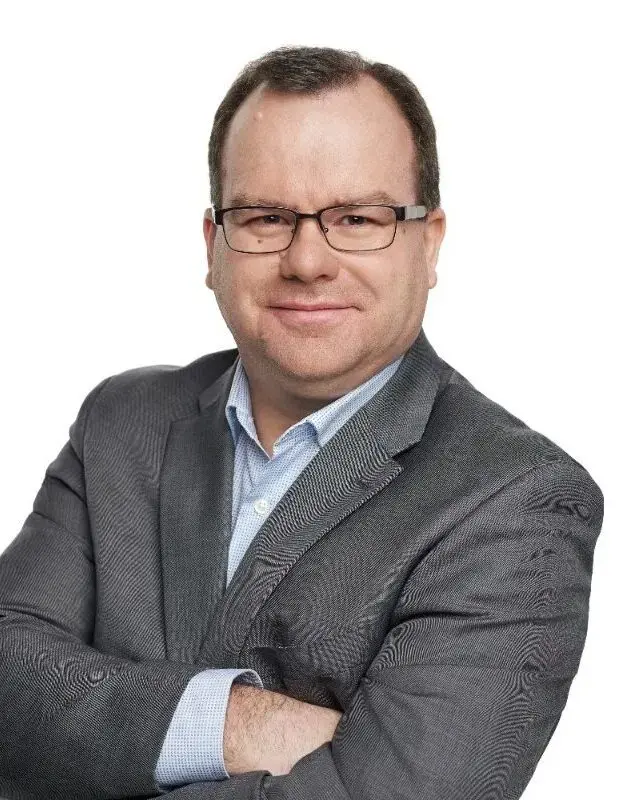
Payments companies are pouring billions into monitoring user behavior after they enter the system. This approach treats fraud as a transaction issue rather than an identity crisis. Digital Commerce Group’s Chief Technology Officer, Paul Twigg, argues that the industry has fundamentally misunderstood where the risk lies. The current strategy focuses heavily on post-entry verification, which creates significant inefficiencies for both banks and merchants.
Breaking news
 Premium Card Evolution: Experiential Value Takes Center Stage
 Rising U.S. Treasury Yields Spark Debt Concerns, But Crisis Remains Unlikely
 Russia Tests Digital Ruble for Government Salary Payments
 Zilch Expands Financial Services with New Membership Tiers and Credit Tools
The prevailing model relies on stacking multiple security layers. Behavioral analytics, device intelligence, and velocity checks operate sequentially. Each new tool is implemented because the previous one failed to stop financial losses. This layering exercise adds complexity without necessarily improving accuracy. Systems monitor what users do once inside the platform, but they often miss who the user actually is before entry.
Why Current Methods Miss the Mark
The current defense mechanism is reactive rather than proactive. When a new fraud vector emerges, developers add another rule or algorithm. This results in a bloated architecture that struggles to keep pace with sophisticated attackers. Device fingerprinting helps identify hardware, but it does not confirm human intent. Velocity checks flag unusual spending patterns, yet they generate false positives for legitimate customers. The result is a system that constantly adjusts thresholds, leading to friction for good users and gaps for bad actors.
Twigg suggests that identity verification must happen earlier in the journey. Instead of analyzing transactions in isolation, firms should establish a robust identity baseline first. If the system knows who the customer is with high confidence, subsequent transaction analysis becomes far more effective. This shift moves the focus from pattern matching to trust establishment. It reduces the need for intrusive step-up authentication during checkout.
Traditional methods assume that every anomaly indicates fraud. This assumption drives up denial rates for valid payments. Customers face repeated challenges, such as one-time passwords or biometric scans. These interruptions increase cart abandonment and reduce overall conversion rates. Meanwhile, sophisticated fraudsters mimic normal behavior to bypass behavioral models. They use stolen credentials and clean devices to blend in. The lack of a strong initial identity check allows these impostors to pass through easily.
The Path Toward Smarter Security
The cost of this misalignment is high. Banks spend significant capital on maintaining complex rule engines. Merchants bear the chargeback fees when fraud slips through. Both parties lose revenue due to declined legitimate transactions. A unified identity framework could streamline these processes. It would allow systems to make faster decisions based on verified trust levels rather than raw data points.
Adopting an identity-first approach requires a cultural shift within payment networks. Teams must prioritize knowing the user over just checking the card. This involves integrating stronger authentication protocols at the point of entry. It also means sharing identity data securely across partners. As digital commerce expands globally, the volume of transactions will continue to rise. The current layering strategy may become unsustainable under this pressure.
Industry leaders are beginning to recognize the limitations of pure transaction monitoring. The next generation of fraud prevention tools will likely blend identity verification with real-time analytics. This hybrid model promises better accuracy and lower friction. For now, the industry remains stuck in a cycle of adding patches to a flawed foundation. Solving the identity problem is the key to unlocking efficient, secure payments.
Frequently Asked Questions
Why do payment firms rely on so many security layers? Firms add new layers because previous tools failed to prevent losses. Each addition addresses specific gaps left by the prior system, creating a complex stack of defenses.
How does identity verification improve fraud detection? Establishing a clear identity baseline allows systems to distinguish between known and unknown users. This reduces false positives and enables faster, more accurate decision-making during transactions.